Market overview and structural significance of the Workplace Transformation Market
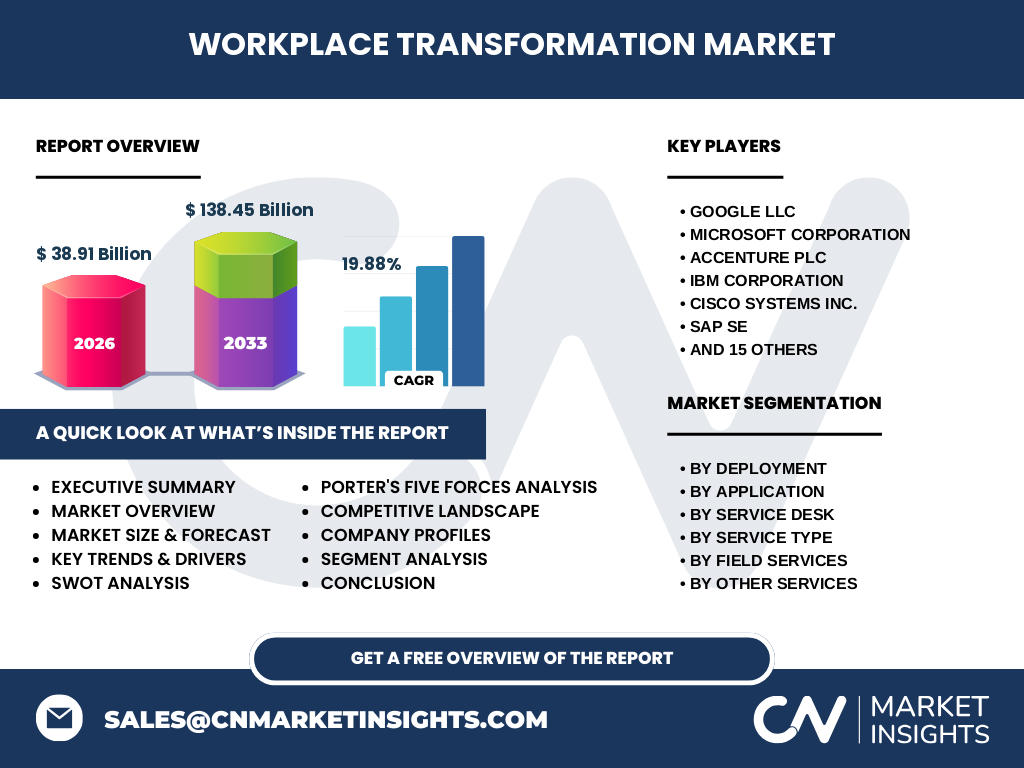
Our analysis indicates the Workplace Transformation Market market size is valued at 38.91 Billion in 2026, expanding into a critical macroeconomic engine. This sector encompasses advanced digital infrastructure, cloud architectures, and unified communication tools designed to modernize enterprise operations. Industry significance stems from its direct impact on organizational agility, compliance adherence, and workforce productivity across regulated sectors.
What core factors drive and restrain the Workplace Transformation Market industry trends?
The market is propelled by accelerating hybrid work models and cloud migration imperatives, yet restrained by legacy infrastructure integration hurdles. Compliance mandates from bodies like the GDPR and HIPAA enforce strict data governance, complicating cross-border deployments. Organizations must navigate severe talent shortages in cybersecurity and desktop virtualization to fully capture enterprise value from automation initiatives.
Emerging growth patterns and technological shifts
The shift toward hyper-automation has accelerated adoption across Robotic Process Automation and Intelligent Document Processing. Enterprises increasingly prioritize Desktop as a Service (DaaS) to secure remote endpoints and reduce hardware lifecycle costs. This trend favors platform providers with robust API ecosystems, enabling seamless integration between legacy databases and modern cloud collaboration suites.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic forced an immediate, emergency pivot to remote operations, fundamentally altering the trajectory of the Workplace Transformation Market analysis. While initial supply chain disruptions stalled hardware upgradation services, subsequent quarters saw unprecedented enterprise investment in Unified Communication And Collaboration tools. Recovery has consolidated around permanent hybrid models, with CIOs institutionalizing pandemic-era digital investments for long-term operational resilience.
Competitive benchmarking and strategic market concentration
The competitive landscape features intense rivalry among tech giants like Microsoft Corporation, Google LLC, and Cisco Systems Inc., alongside enterprise service leaders such as Accenture plc and IBM Corporation. Market concentration is moderate-to-high, with platform vendors bundling security and AI-driven workflow automation to increase switching costs and capture higher wallet share from Fortune 500 clients.
Executive summary of key findings
Our research projects the Workplace Transformation Market industry trends to surge from 38.91 Billion in 2026 to 138.45 Billion by 2033, representing a robust CAGR of 19.88%. Growth is heavily anchored in cloud-based deployments and AI-powered service desks. Strategic alignment with zero-trust security frameworks and employee experience enhancement will dictate long-term leadership in this expanding ecosystem.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the market will experience exponential acceleration, moving from 2026 baseline figures to reach 138.45 Billion by 2033 at a 19.88% CAGR. This trajectory is fueled by mandatory cloud migrations, escalating enterprise mobility requirements, and the integration of generative AI into routine workflow automation and incident management services.
Granular segmentation analysis across deployment and applications
Segmentation spans deployment models (On Premise, Cloud Based, Hybrid), applications (Digital Transformation, Remote Work Enablement, Employee Experience), and specialized services. Cloud-based deployments lead market absorption due to scalability demands. Meanwhile, enterprise mobility and telecom segments dominate telecom expense management and unified endpoint management across global operations.
Geographic distribution and regional performance dynamics
Regional performance varies significantly, driven by local regulatory frameworks, broadband infrastructure maturity, and enterprise density. North America maintains the dominant revenue share, underpinned by early adoption of advanced IT infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by rapid digitization initiatives in manufacturing and BFSI sectors across emerging economies.
In-depth regional review of high-growth territories
In North America, stringent compliance standards set by agencies like NIST accelerate investments in secure cloud migration and automated auditing. Conversely, the European market prioritizes stringent data sovereignty under EU directives, boosting demand for localized hybrid deployment models and robust license management systems across enterprise accounts.
Strategic company profiles and market positioning
Industry leaders employ distinct strategies: Salesforce Inc. and Workday Inc. dominate employee experience platforms, while ServiceNow Inc. leads IT service management and workflow automation. Hardware and infrastructure titans like Hewlett Packard Enterprise and Cisco Systems Inc. focus on secure edge computing and advanced video conferencing services to capture enterprise hardware upgradation budgets.
Porter's Five Forces analysis of the competitive landscape
Industry rivalry is intensely high, driven by frequent product launches from tech titans like Zoom Video Communications Inc. and Zoho Corporation. Threat of substitution remains moderate, constrained by complex enterprise workflow dependencies. Bargaining power of buyers is significant among large enterprises demanding customized hybrid integration, while supplier power is mitigated by open-source alternatives.
SWOT analysis of the Workplace Transformation ecosystem
Key strengths include scalable cloud architectures and advanced AI automation. Weaknesses involve complex legacy system migrations. Opportunities abound in SME digital adoption and intelligent document processing. Threats encompass escalating cybersecurity vulnerabilities, geopolitical trade restrictions affecting hardware supply chains, and stringent international regulatory shifts.
Value chain analysis from raw materials to enterprise end-users
The value chain originates with semiconductor manufacturers and raw material suppliers for endpoint hardware, flowing through software developers, cloud providers, and system integrators like Tata Consultancy Services, Infosys Limited, and Wipro Limited. These integrators deliver customized workplace automation and field services directly to enterprise end-users in BFSI and healthcare.
Strategic investment insights and high-potential focus areas
Investors should target niche innovators specializing in Intelligent Document Processing and automated compliance auditing. High-potential areas include SME-focused Desktop-as-a-Service platforms and automated incident management solutions. Partnerships with global system integrators such as Capgemini SE and HCL Technologies offer viable pathways for market penetration.
Conclusion and key strategic takeaways for market stakeholders
The data demonstrates that reaching 138.45 Billion by 2033 requires continuous innovation in AI-driven workflow automation and robust cybersecurity. Stakeholders must pivot toward flexible hybrid models and comprehensive managed services to capture expanding enterprise budgets in digital modernization and employee experience enhancement.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with enterprise CIOs, and secondary macroeconomic indicators. We cross-reference financial filings from key players like Atlassian Corporation Plc and Dropbox Inc. with regional IT spending reports to ensure absolute forecast accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics across deployment types, service desks, enterprise sizes, and end-use industries from 2026 through 2033. Limitations include unforeseen macroeconomic volatility, shifting geopolitical trade tariffs on hardware components, and rapid, unpredictable shifts in artificial intelligence regulatory policies across major global jurisdictions.
Recent strategic developments, partnerships, and product launches
Recent market activity highlights aggressive M&A and strategic partnerships aimed at integrating generative AI into workplace automation platforms. Key ecosystem participants have launched advanced unified endpoint management tools and enhanced compliance and audit services to address tightening global data privacy regulations and evolving hybrid workforce security demands.